TL;DR
- Asked which use case will see the first large-scale impact from new forms of digital money, attendees chose the settlement of tokenized assets, ahead of cross-border payments, corporate treasury and retail payments. Panellists added cross-border payments and treasury as close behind.
- Panellists described stablecoins, tokenized deposits and wholesale central bank money as complementary, with a trade-off between counterparty risk and accessibility.
- Tokenized deposits work well inside a bank but cannot move freely between banks without rebuilding clearing and netting, which led one panellist to expect stablecoins to carry money between institutions.
- Stablecoins still lack the treatment of cash in many rules, from collateral at central counterparties to accounting and prudential ratios.
- Instant, always-available settlement puts pressure on operations and on pre-funding, and panellists pointed to intraday credit through DeFi lending as one answer.
- Panellists see little or negative return on investment today and treat digital money as a long-term, defensive move, with forecasts ranging from half the market tokenized by 2030 to a real market only a decade away.
Speakers
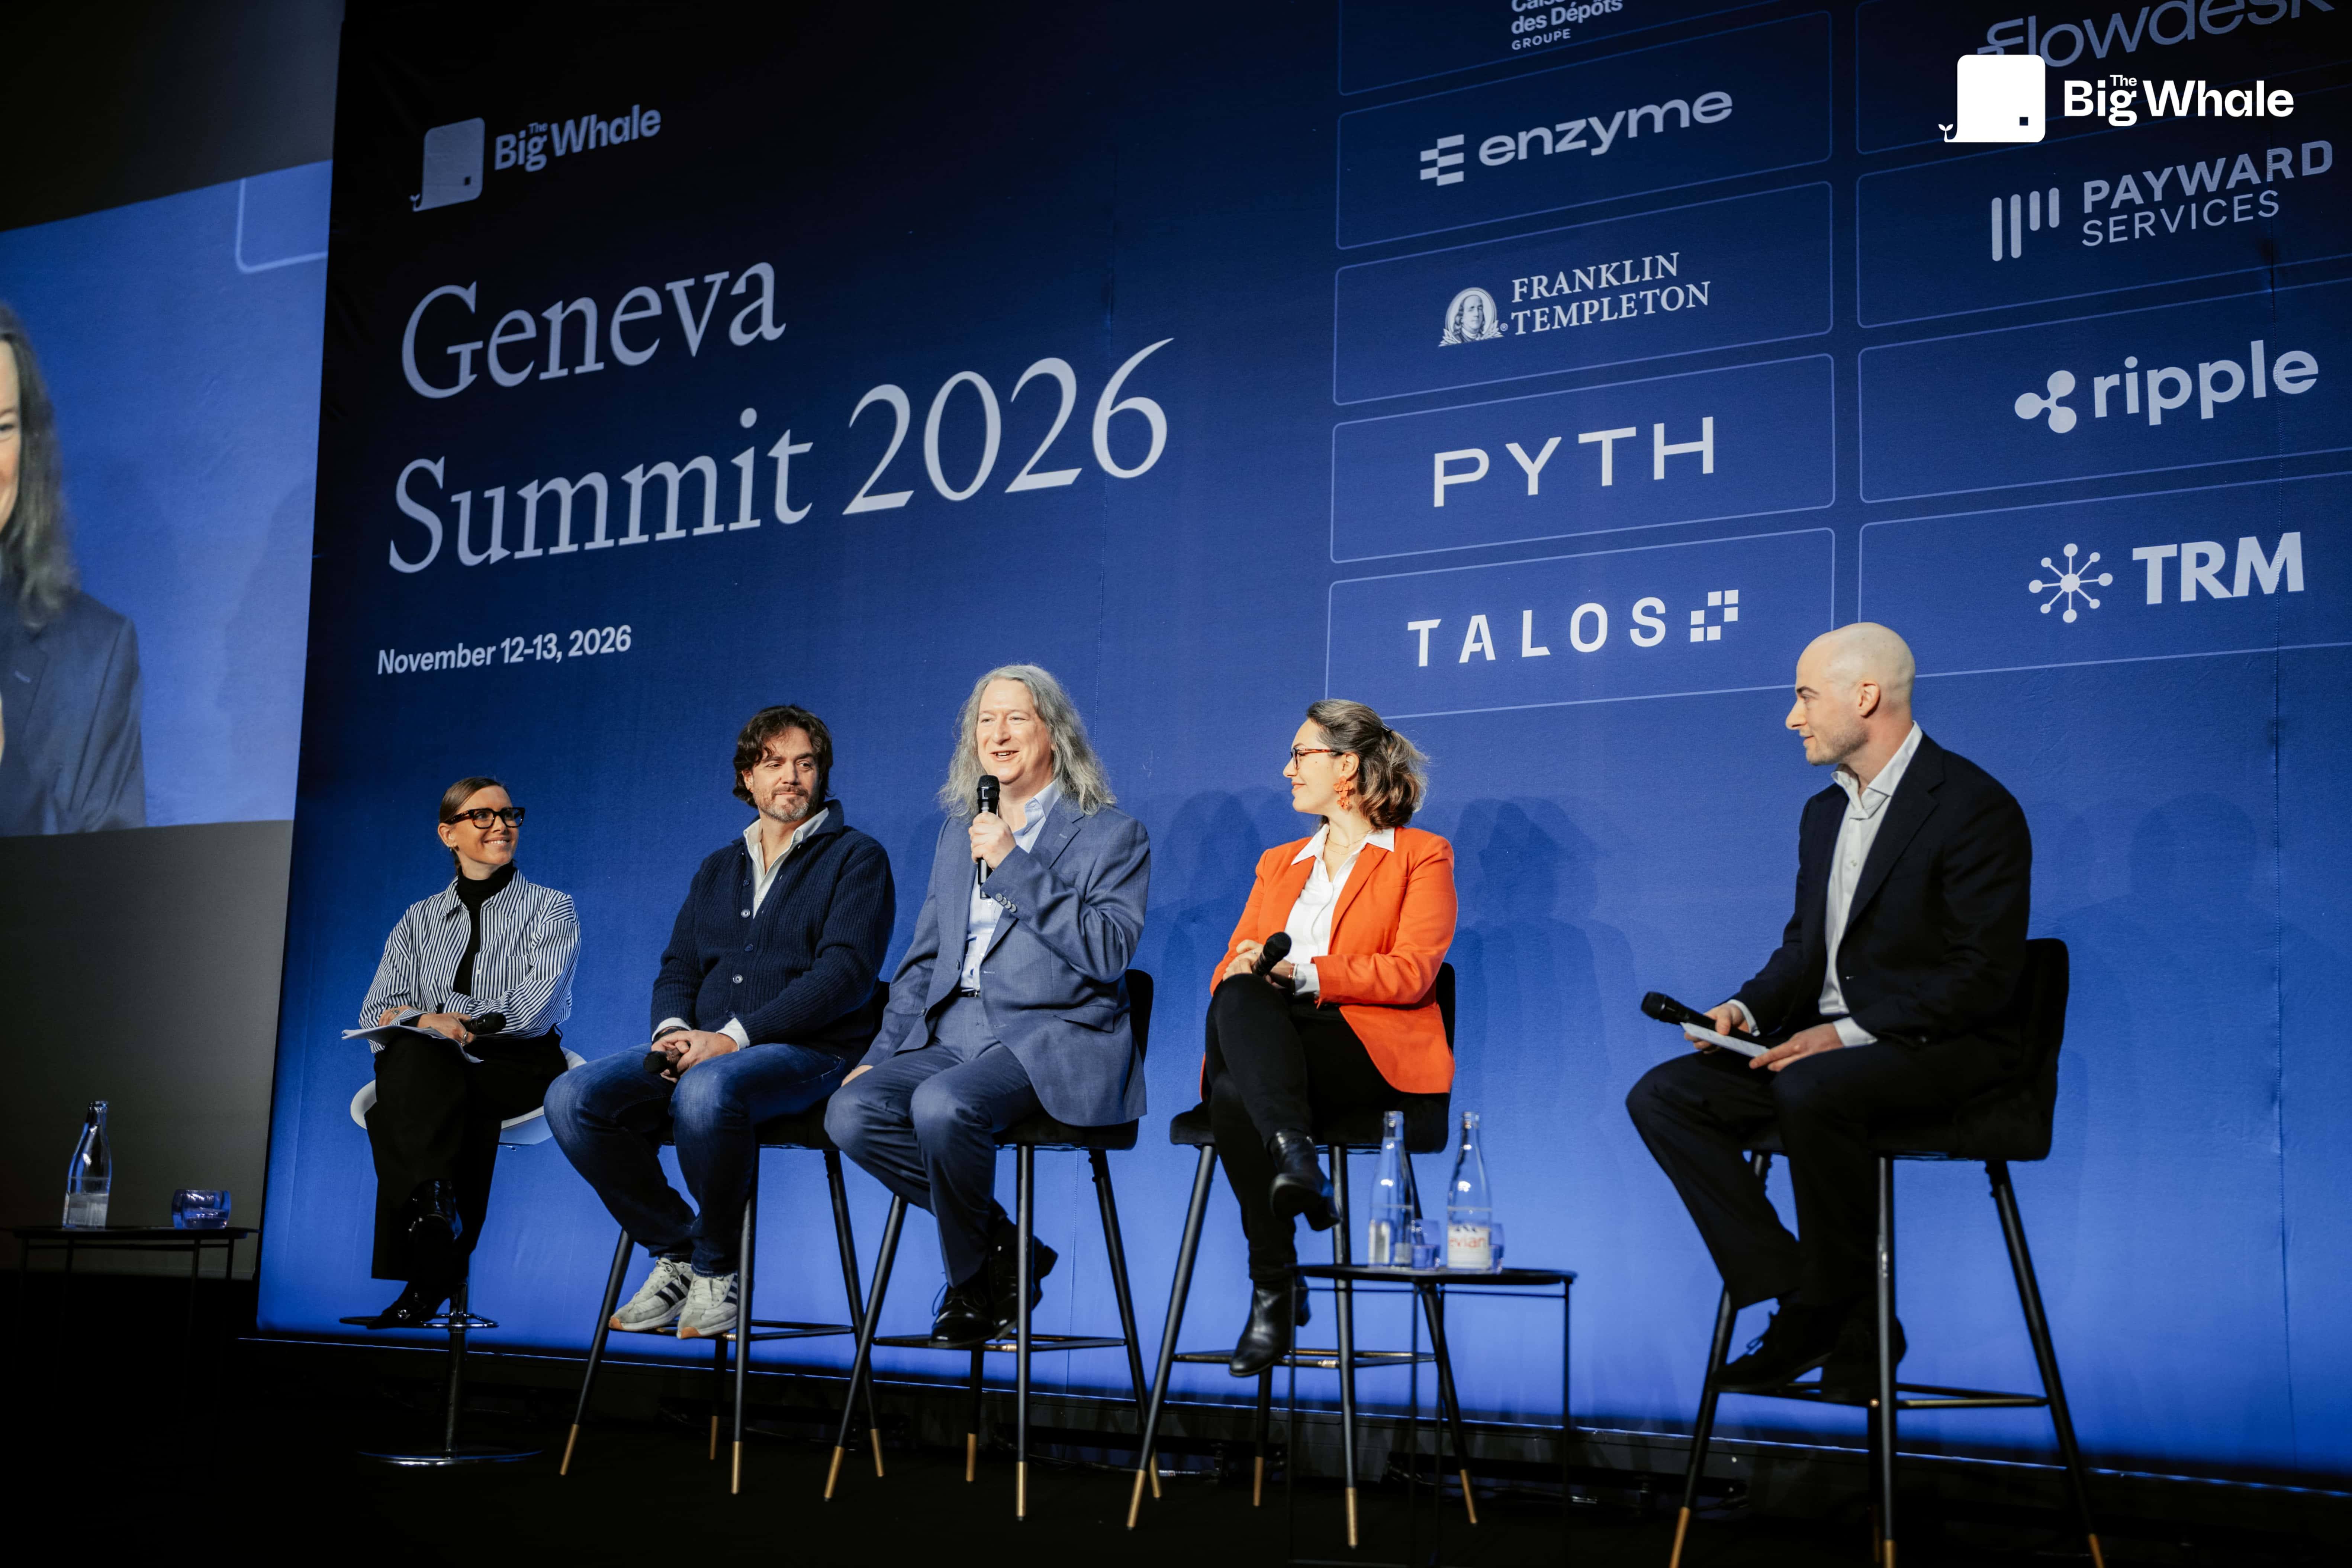
Stablecoins, Tokenized Deposits: Too Many Forms of Digital Money, Not Enough Use Cases?
- Stéphanie Cabossioras, Chief Strategy & Global Policy Officer at SG Forge
- Emma Lovett, Executive Director, Markets DLT - Credit Lead at JPMorgan
- Nick Kerigan, Managing Director, Head of Innovation at Swift
- Julien Clausse, Digital Asset Products and Strategy at BNP Paribas
The Summit was held under the Chatham House Rule: statements are reported without attributing them to a named speaker or affiliation.
Which use case comes first?
In a poll before the panel, attendees picked the settlement of tokenized assets as the use case where new forms of money will first have a large-scale impact. A panellist from a US bank agreed: settling a trade in fiat handles the cash leg almost automatically today, and tokenized assets will need an onchain equivalent. This panellist expects institutions to have a stablecoin of choice in each currency, used by default to settle trades, and noted that stablecoins are established while tokenized deposits are not yet.
A panellist from a bank's stablecoin issuer would have chosen the first three options together, since cross-border payments, settlement and treasury are linked, and added a use case missing from the poll: giving crypto markets a bank-issued, regulated settlement asset. A panellist from a payments network agreed with the same three use cases, and said its shared ledger started with tokenized deposits from banks that already had them live, to reach live transactions quickly. As a cooperative, the network will also work with stablecoins if its members want them.
Three forms of money, one trade-off
A panellist from a large European bank gave two reasons to tokenize cash: moving it across networks of participants that are not otherwise connected, and settling atomically against tokenized assets. The bank works on all three forms of digital money, alongside fiat:
- Tokenized deposits, with the bank as counterparty, used with a large Asian corporate for liquidity management
- A euro stablecoin through a consortium of European banks, with a private issuer as counterparty
- Wholesale central bank money, through the Eurosystem's work on settlement
For this panellist, the three are complementary: stablecoins carry high counterparty risk and high accessibility, wholesale central bank money the reverse. A €1 billion bond will not settle in a stablecoin.
Asked whether the US bank would accept another bank's stablecoin as the cash leg of a $100 million trade in tokenized bonds, the US bank panellist said a bank-issued stablecoin introduces a different credit risk from dollars, and that the market is not established enough to know how this will work.
Why tokenized deposits struggle to leave the bank
The stablecoin issuer panellist explained the bet on stablecoins: they move value instantly, 24/7 and across borders, which today's payment systems cannot do. Their limit is that regulation does not yet treat them as cash:
- As collateral at central counterparties, as a settlement asset in market infrastructures, as the cash leg of investment funds and in company accounts
- In prudential rules, where regulated stablecoins should count as high-quality liquid assets, and where the treatment of their reserves should not reduce banks' capacity to lend
Tokenized deposits face two problems, according to the same panellist. In Europe, no rule defines them or states that they are treated like ordinary deposits. They also cannot move freely between banks: each transfer would create an exposure of one bank to another, so clearing and netting would have to be rebuilt between all banks and currencies. Tokenized deposits suit large banks with many internal systems and clients, and smaller banks gain less. A stablecoin is a bearer instrument bridging the banking system and a blockchain, while a tokenized deposit is created on the new ledger but stays within the banking system. This panellist expects tokenized deposits to develop inside banks and stablecoins to carry money between them.
The payments network panellist described its shared ledger as an orchestration layer between banks: the receiving bank can credit its client immediately, and banks can net their transactions before settlement. Use cases have moved faster than expected, from interbank payments to a corporate treasury transaction and, most recently, dollar payments at weekends. For this panellist, clients care about moving money when they want, more than about the technology.
Always available, and the cost of being instant
The payments network panellist warned that 24/7 service means every participant in the chain must operate around the clock, with staff, systems, maintenance windows and outage plans to match, and expects automation and AI agents to help. The European bank panellist prefers to speak of availability on demand, driven by clients used to self-service, and stressed that what matters is what happens before and after a transfer: travel rule checks, accountability and reporting.
On pre-funding, the US bank panellist said instant settlement puts pressure on banks and clients alike, since markets move quickly and T+2 gives time to arrange cash and securities. The technology allows instant settlement and the removal of some intermediaries, but it is not clear the market wants either. The stablecoin issuer panellist expects clearing to remain where markets choose it, followed by instant settlement, and pointed to peer-to-peer repo through DeFi lending protocols, where holders of financial assets can get intraday credit. The issuer opened a lending vault on a DeFi protocol where holders of its euro and dollar stablecoins lend against Bitcoin, Ether or a tokenized money market fund, a test of collateral management that would be harder to run in regulated infrastructures today.
For the European bank panellist, any asset other than a native crypto token needs a trusted party off-chain to prove what backs it, which remains the role of banks. The change is a more open business architecture, with several asset types on the same ledger able to interact, and assets used as utility as well as stores of value. The payments network panellist added that faster recycling of money will create new liquidity businesses, still served by trusted institutions. The US bank panellist noted that colleagues outside digital assets struggle to picture this world, and called for as many assets as possible on these networks to build scale.
Forecasts and returns
Asked for a number, the US bank panellist expects 2028 to disappoint and tokenized assets and cash to reach about half the market by 2030. The payments network panellist quoted the idea that change takes longer than expected but has more impact in the end, and noted that every consulting estimate for 2030 ends in trillions. The European bank panellist sees a generational shift: an explosion of tokenized deposit products over the next two years, then consolidation and interoperability, and a real market about ten years away. The stablecoin issuer panellist predicted Bitcoin at $200,000 in 2028, arguing that innovation and funding in traditional finance follow crypto market cycles.
On return on investment, the US bank panellist described it as low to negative today, with tokenization a long-term and partly defensive play, unlike crypto products that scale faster. The payments network panellist said a cooperative exists to stay useful to its members more than to maximise return. For the European bank panellist, blockchain will cost more than it saves, and the point is to secure a position in a new value chain. The stablecoin issuer panellist sees scale as a network effect: if every institution in the room opened wallets for its clients, all would benefit.
Conclusion
Asked who else gets onchain money right, the US bank panellist cited a commercial paper transaction settled with a stablecoin last December, the payments network panellist named institutions that learn by doing, the European bank panellist pointed to crypto-native firms that build products such as tokenized money market funds from scratch, and the stablecoin issuer panellist cited other French banks and a European central securities depository working to accept stablecoins as a settlement asset. Panellists agreed that the forms of digital money will coexist, each matched to a use case, and that legal treatment, interbank movement and round-the-clock operations will decide how fast they scale.