TL;DR
- In a poll before the panel, 52% of attendees saw tokenization as a more efficient version of today's system and 48% as a new financial system. Most panellists placed themselves in between, and one argued that tokenization itself changes little and that the value lies in programmability.
- Panellists described deep internal change: procedures rewritten for funds that run 24/7, every workflow reopened, and a rethink of the asset manager's role as money becomes digital.
- For tokenized money market funds, panellists see regulation and the cash leg in place in many jurisdictions. The argument that wins clients over is the absence of a cut-off time.
- Infrastructure costs worry the industry: firms need their providers to survive, while clients expect prices close to today's near-free custody.
- On who should hold the record, panellists agreed that wholesale markets need an accountable, regulated and neutral entity.
- The missing pieces are programmability in real use, institutional wallets and real liquidity onchain. Bonds, government debt and tokenized equities were named as the next growth areas.
Speakers
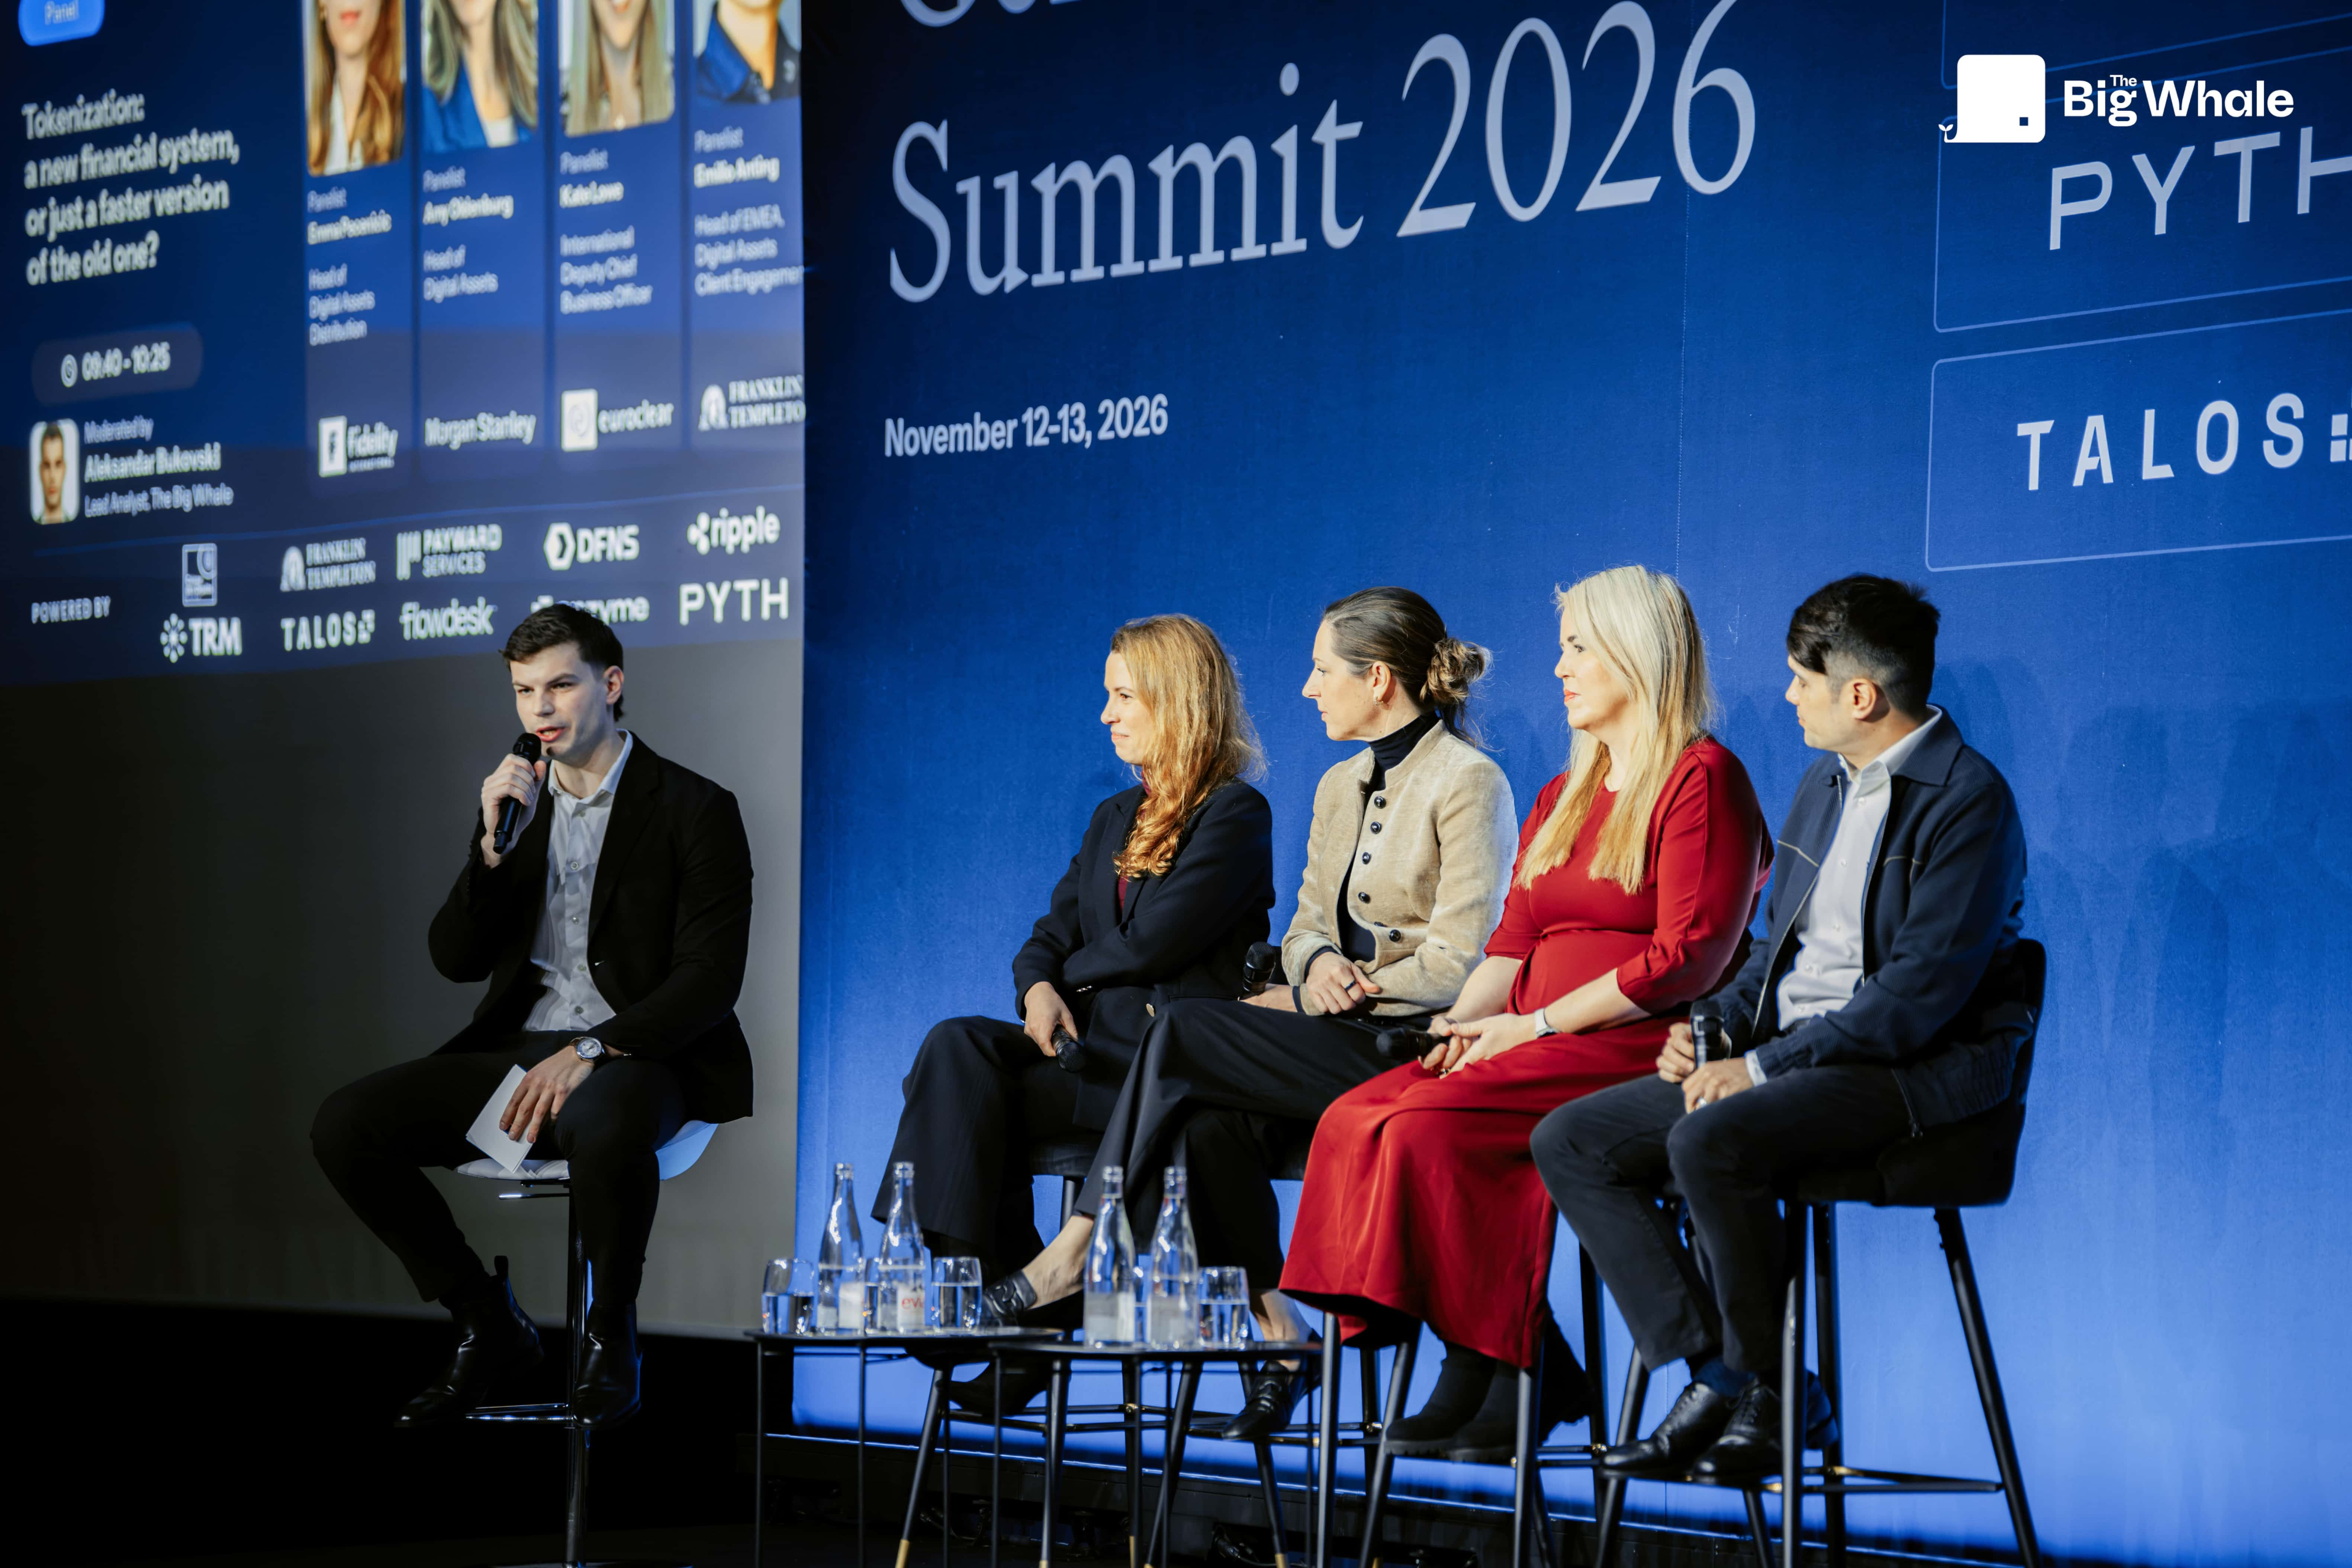
Tokenization: A New Financial System, or Just a Faster Version of the Old One?
- Emma Pecenicic, Head of Digital Assets Distribution at Fidelity International
- Amy Oldenburg, Head of Digital Assets at Morgan Stanley
- Kate Lowe, International Deputy Chief Business Officer at Euroclear
- Emilio Anting, Vice President of Digital Asset Partnerships at Franklin Templeton
The Summit was held under the Chatham House Rule: statements are reported without attributing them to a named speaker or affiliation.
Somewhere in between
Panellists mostly rejected the choice offered by the poll:
- A panellist from an asset manager expects the financial system to be rebuilt over the long term on blockchain-based capital markets, step by step. The firm launched a tokenized dollar liquidity fund this year because clients wanted to settle onchain around the clock, and some links in the chain are being rebuilt with APIs and existing technology rather than onchain
- A panellist from a global bank answered both: equity markets work well and have moved towards T+1 without tokenization, while programmability, including vaults, opens products that could not be built before
- A panellist from a market infrastructure answered neither. Representing value digitally and sharing it across a network is what securities depositories have done for twenty years, with atomic settlement already running every day in one of them. What matters is making existing assets programmable, so they can be mobilised faster as collateral and work harder for their owners
- A second asset manager panellist expects a gradual shift from accounts to wallets, unlocked by specific use cases such as intraday repo and collateral for trading
What tokenization changed inside the firms
For the first asset manager panellist, the strategy comes from the top, but launching a 24/7 fund still meant rewriting about fifteen procedures, creating new ones for fees, blockchain selection and smart contract reviews, and explaining to a portfolio manager why a login might be needed on a Sunday. The bank panellist said tokenization forced the firm to reopen every workflow of every asset class: after fifteen years focused on stability since the financial crisis, few people still knew how each workflow actually runs. AI and 24/7 trading add to the pressure, and the hardest budget to defend is the upgrade of existing systems, while executives also want to protect current revenue.
The second asset manager panellist described a rethink of the asset manager's role: how investment products interact with money that moves instantly, and how assets can serve as utility, for collateral or onchain treasury, as well as a store of value. For the market infrastructure panellist, blockchain brought competition: it raised the question of whether securities depositories are needed at all, and forced them to show how they add value. A shared ledger could also give clients a single view of assets held across several depositories that today run on different technology stacks.
Tokenized money market funds: from $15 billion to $600 billion?
The moderator noted that tokenized money market funds hold about $15 billion today, against a projection of about $600 billion by 2030 shared by the first asset manager panellist, a 40-fold gap. That panellist sees an inflection point:
- Regulation allows tokenized funds to be issued from Luxembourg, Ireland, offshore centres, Hong Kong, Singapore and the US, so it is no longer an excuse
- The cash leg is available through stablecoins and bank payment networks running 24/7
- Clients react most to the absence of a cut-off time, for example corporate treasurers in Asia who can settle a dollar product during their own morning
The bank panellist compared the market to the early days of mail-order DVD rentals: most clients still have the equivalent of a VHS player, the infrastructure to use these products. The industry needs to explain the value to end clients, such as same-day settlement to meet a capital call, no cut-off times and yield that starts accruing almost immediately, including at weekends. The second asset manager panellist described tokenized money market funds as the entry point to tokenized assets, with yield accruing to the second as the token moves across the ecosystem.
The cost of new rails
Asked whether companies in the sector generate sustainable cash flows, the bank panellist named it a major worry: banks need infrastructure providers to survive if their technology is strategic, while clients compare prices with today's custody fees, which are close to zero. The panellist compared it to telephone bills: households pay far more for phones than decades ago, while a basic call has become almost free, because the value lies in everything else the network allows. The second asset manager panellist agreed that the productivity gains justify the cost and said infrastructure has to be made to work harder.
Who should hold the record?
The second asset manager panellist described a fund whose register sits on a public blockchain while a regulated transfer agent within the group keeps control of the records, with the ability to verify and burn tokens. For this panellist, the location of the record matters less than the accountability of whoever holds it. The market infrastructure panellist agreed: in wholesale markets, participants will want a legal person to call when something goes wrong, as depositories do today in sanctions or defaults, and not a chain that needs months of consensus before it can be forked. New types of digital securities depositories may appear, but regulation is what makes them trusted, and the record keeper must be neutral, since competitors will not accept a network run by one of them. Securities depositories are slow partly because they are heavily regulated, which is also why clients trust them.
Promises not yet kept
Panellists named what is still missing:
- The bank panellist wants to see programmability deliver a second phase of value that was impossible before
- The first asset manager panellist described three stages, hold, use and build, and placed the market between the first two. The firm publishes fund data onchain so that others can build products on top of it, although nobody uses it yet
- The second asset manager panellist called for wallet adoption by institutions, with global systemic banks offering wallets next to traditional accounts
- For the first asset manager panellist, retail investors should not need to know whether a product is tokenized at all
- The market infrastructure panellist pointed to real liquidity onchain, citing the move of the French commercial paper market, about €310 billion, with all its participants. A token nobody can buy or use as collateral is useless
Conclusion
Asked which segment will grow most by November 2027, the bank panellist chose government debt, from US Treasuries to Japanese government bonds and UK gilts, while warning that products giving offshore investors access to US assets remain largely unregulated. The first asset manager panellist expects $50 to $100 billion in tokenized liquidity products next year, with tokenized equities and ETF shares growing faster from a lower base, driven by Asian demand for US assets. The second asset manager panellist added tokenized equities as collateral for securities lending, and the market infrastructure panellist chose bonds, simple instruments with well-understood workflows, where liquidity will follow if the largest players move together. Panellists placed the value of tokenization in what assets can do once liquidity, wallets and accountable record keepers are in place.